
BLACKMORE TECHNOLOGY GROUP LIMITED / KNOWLEDGE CAPITAL ECONOMY / OCTOBER 2026
PART VI · COMMERCIAL ECONOMICS

BTG Technology Asset and Usage Economy

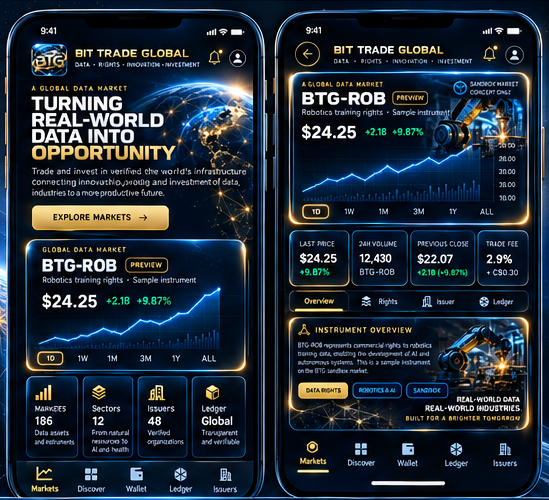
Illustrative BTG visual for economic-model

The Knowledge Capital Economy proposes a change in starting point: make a useful knowledge asset identifiable and testable before building the entire commercial story around a company. Its value depends on productive usefulness, enforceable rights, customer demand and the cost of delivering the service. Market size is context, not a balance sheet or an investor return.

MARKET AND REVENUE FOUNDATIONS

Economic values that must never be combined

Market research is context, not BTG turnover

The dossier derives approximately US$124.84 billion in 2025 North American data-broker industry revenue from a separate global research estimate and regional share. Statistics Canada’s 2019 data-asset investment and the U.S. BEA’s experimental 2024 data-capital measures concern different years and definitions. These figures cannot be added to create an Exchange revenue forecast or an implied volume of publicly traded data securities.

Three actual-money flows must remain distinct

Commercial customer receipts arise when an authorized licence or service is delivered and paid for. Investment subscriptions, when lawfully issued, finance the issuer and are not operating sales. Dividends or other shareholder entitlements require actual legal rights, available funds, applicable corporate action and accounting approvals. A user’s proposed contributor royalty is a separate contractual allocation from collected distributable cash.

Pricing and fees require real economics

The draft 2.9% plus C$0.30 commercial transaction fee is a proposal, not established net margin. Processor charges and servicing expenses can consume the entire gross fee for small transactions. Valuation methods should distinguish independent estimates, executed licence income, indications of demand, regulated securities prices and issuer enterprise value, always with date, source, currency, unit and uncertainty.

COMMERCIAL ECONOMICS

Section 01 / 05

The individual asset has several different economic measures

A machine-maintenance method could have a known development and replacement cost, a technical benefit measured against the customer’s current process, a price another party offers for a scoped licence and potentially a record of repeat usage. Those measures cannot be added together as though they were one transaction. The valuation method, original source, assumptions, date and the person performing the analysis need to be disclosed.

There is also a difference between the value of the capability and the value of a business commercializing it. A company pays for hosting, support, legal work, development, customer acquisition, insurance, technical verification and staff. Its enterprise valuation would consider costs and liabilities, not simply the possible gross market size of data.

Section 02 / 05

What the Exchange can and cannot earn

Commercial income could include legitimately contracted access to DataChips, Circuits, controlled datasets or service results; optional enterprise functionality; and platform services agreed with participating parties. The exchange operator’s fees, a contributor’s royalty, a developer’s licensing income and an investor’s dividends are different flows with different accounting and legal obligations.

The whitepaper records a proposed charge of 2.9% plus C$0.30 for completed commercial transactions. That figure is not established profit. If an external processor charges a similar amount, the gross platform fee may be largely consumed before fraud prevention, security, refunds, support or other expenses. Small machine-to-machine transactions may require batching, prepaid balances or contract pricing.

Section 03 / 05

Contributor participation follows actual contracts and receipts

If a permitted dataset or method helped create a commercial asset, a contributor may receive agreed proceeds where an enforceable arrangement grants them. Each allocation starts from the correct settled receipt and any contractually allowed deductions, taxes, refunds and reserves. A repeated path through a software dependency graph must not multiply the same royalty into an impossible liability.

A contributor’s claim to proceeds should be traceable to the particular right they supplied. Supplying research data does not necessarily make that person or institution the owner of algorithms generated from it. Similarly, a voluntary data permission does not grant automatic perpetual entitlement to every future downstream application.

Section 04 / 05

Why reusable knowledge might compound

Once a qualified capability can be rebuilt reliably, different customers or research labs may save the cost of starting from scratch. The next lab can compare a new design with the retained baseline; even a failure can prevent repeated work when its evidence is valid and relevant. This is the proposed compounding mechanism: verified work reduces the cost of new verified work.

A real gain exists only when those savings exceed the cost of qualification, maintenance, governance, storage and licensing. Thousands of internal FarmNode identities would not prove a new market or productivity advantage. The meaningful measures are externally useful inventions, independent reproductions, operating costs, repeat customers and honest failure rates.

Section 05 / 05

Financing must follow the issuer and regulatory rules

A business built around proven rights to a useful invention may be able to demonstrate customers, savings and a credible development plan to funders. That is an asset-first capital-formation thesis. It is not permission to sell shares directly from a data wallet. Issuers, offering rights, transfer restrictions, disclosures, investor protections and relevant market or dealer authorizations are separate prerequisites.

Any economic model presented on the site should distinguish scenario calculations from bank-reconciled results. The whitepaper’s data-broker market sources, Canadian intangible-capital studies and U.S. experimental data-asset estimates measure different things. They cannot be combined into a single estimate of BTG’s revenue or the market capitalization of candidate DCOs.

What the records must establish

Facts that belong in the supporting evidence

Technical productivityMeasured benefit against an actual customer baseline
Commercial volumeThird-party agreements and settled usage receipts
Operator marginGross receipts less processors, support, infrastructure and compliance
Contributor payoutEnforceable agreements and permitted net distributable receipts
Investment valueIndependent issuer disclosures and lawfully issued interests